by Ariful | Mar 17, 2026 | UK Updates
The Big Headline: The Federal Tax Rate Drop to 14%
The most impactful change for 2026 is the full implementation of the federal tax rate cut. While the transition began in mid-2025, 2026 marks the first full calendar year where the lowest federal tax bracket has been reduced from 15% to 14%.
This might seem like a small 1% shift, but for small business owners and individual taxpayers, it represents a meaningful reduction in your overall tax burden. This rate applies to the first $58,523 of your taxable income. If you are a business owner paying yourself a salary, this change directly impacts your personal take-home pay and your company’s payroll tax calculations.
Why This Matters for Your Cash Flow
Lower taxes at the bottom bracket mean more immediate liquidity. However, this also means your payroll software and accounting systems must be updated to reflect these new rates. If you are still using 2025 formulas, you might be over-remitting to the CRA, which essentially gives the government an interest-free loan of your money.
2026 Federal Tax Brackets: The New Landscape
To account for inflation and maintain purchasing power, the CRA has indexed all tax brackets upward by 2%. This “bracket creep” protection ensures that if your income rose slightly to keep up with the cost of living, you aren’t pushed into a higher tax percentage unnecessarily.
Here is the breakdown of the federal tax brackets for the 2026 tax year:
| Taxable Income Range |
2026 Federal Tax Rate |
| First $58,523 |
14% |
| Over $58,523 up to $117,045 |
20.5% |
| Over $117,045 up to $181,440 |
26% |
| Over $181,440 up to $258,482 |
29% |
| Over $258,482 |
33% |
Note: These are federal rates only. You must also factor in your provincial or territorial tax rates, which vary significantly depending on whether you are based in Ontario, British Columbia, Quebec, or elsewhere. Navigating these layers can be complex, especially for international entrepreneurs. If you are a non-resident managing a Canadian entity, you might want to learn more about how tax works for a foreign director to ensure you are meeting all cross-border obligations.
Maximum Your Savings: New TFSA and RRSP Limits
Investing back into your future is a core part of a smart tax strategy. The CRA has increased the contribution limits for registered accounts for 2026, offering more “tax-free” or “tax-deferred” space.
1. Tax-Free Savings Account (TFSA)
The annual TFSA contribution limit for 2026 is $7,000. If you have been a Canadian resident since the TFSA was introduced in 2009 and have never contributed, your total cumulative room is now higher than ever. Using this space is a “no-brainer” because any investment growth or withdrawals are completely tax-free.
2. Registered Retirement Savings Plan (RRSP)
The maximum RRSP contribution limit has jumped to $33,810 for 2026 (up from $32,490 in 2025). Remember, your individual limit is capped at 18% of your earned income from the previous year, up to this maximum. Contributing to an RRSP is one of the most effective ways to drop your taxable income into a lower bracket.
Immediate Action: Mark Your Deadlines
Missing a CRA deadline is the fastest way to lose your hard-earned profits to interest and penalties. As we move through 2026, here are the dates you cannot afford to forget:
- April 30, 2026: Deadline to file 2025 personal income tax returns and pay any balances owing.
- June 15, 2026: Deadline for self-employed individuals to file their 2025 returns. Crucial: Even though you have until June to file, any taxes owed were still due by April 30. Interest starts accruing on May 1st.
- Monthly/Quarterly: GST/HST remittances. If your business is registered for GST/HST, your filing frequency depends on your annual revenue.
Don’t wait until the week before these dates to get your paperwork in order. If you’re feeling overwhelmed by the volume of receipts and invoices, it might be time to ask: when should you hire an accountant? Early preparation is the difference between a smooth filing and a stressful audit.
Business Compliance: Moving Beyond Bookkeeping
For Canadian corporations and SMEs, compliance is more than just “doing the books.” The CRA is increasingly focused on digital transparency. A growing trend toward real-time reporting and digital integration is reshaping how businesses must manage their tax obligations.
From daily bookkeeping to calculating your precise tax liability, proper compliance ensures that your data is transformed into accurate, ready-to-file returns.
If your business operates across borders—perhaps selling into the UK or Europe—you also need to manage international VAT requirements alongside your Canadian obligations. Understanding the nuances, such as VAT sales vs non-VAT sales, is vital to ensuring your global pricing strategy remains profitable.
GST/HST and the Small Supplier Threshold
If you are a new business owner in 2026, keep a close eye on your “Small Supplier” status. Generally, once your taxable revenues exceed $30,000 in a single calendar quarter (or over four consecutive quarters), you must register for GST/HST.
Failing to register when required can be a costly mistake, as the CRA will hold you liable for the tax you should have collected from your customers, even if you didn’t actually charge them. This is similar to the risks faced by UK businesses; you can read more about what happens if you go above the VAT threshold to see how these tax principles apply internationally.
Your 3-Step Quick-Start Checklist
Don’t let the changes paralyze you. Do these three things first:
- Update Your Payroll: Ensure your 2026 withholdings reflect the new 14% base rate and indexed thresholds.
- Max Your Contributions: Schedule your $7,000 TFSA contribution and calculate your RRSP room based on your 2025 Notice of Assessment.
- Audit Your Records: Ensure your bookkeeping for the year is organized and current so nothing slips through the cracks when filing season arrives.
by Ariful | Mar 17, 2026 | Tax & Accounting
Operating an E-commerce Business in Australia: ATO Compliance in 2026
Operating an e-commerce business in Australia is more complex than just picking winning products and running high-converting ads. By 2026, the Australian Taxation Office (ATO) has refined its digital surveillance to a level that was unimaginable a few years ago. If you think your Shopify sales, Amazon payouts, or Stripe transfers are invisible to the taxman, it is time to think again.
The ATO’s sophisticated data-matching programs are specifically designed to catch discrepancies in the e-commerce sector. At Sterlinx Global, we see firsthand how easily a small oversight can escalate into a full-scale audit. Whether you are a local Australian entity or an international brand selling into the Aussie market, staying compliant requires more than just luck, it requires precise, ongoing compliance.
In this guide, we will break down the most common Australian tax mistakes that trigger ATO red flags and how our global tax compliance suite can keep your business protected.
1. The Data-Matching Dragon: Platform Revenue vs. BAS
The single biggest mistake e-commerce sellers make is assuming the ATO only knows what you tell them. In reality, the ATO receives data directly from platforms like Amazon, eBay, Shopify, and Etsy, as well as payment processors like PayPal, Stripe, and Afterpay.
If the total revenue reported on your Business Activity Statement (BAS) does not align with the data the ATO receives from these third parties, an automated flag is generated.
Why this happens:
- Gross vs. Net Reporting: Many sellers mistakenly report the “net” amount deposited into their bank account (after fees) instead of the “gross” sales amount.
- Multiple Channels: Forgetting to aggregate sales from a smaller, secondary platform.
- Timing Discrepancies: Not accounting for sales made at the end of a quarter that haven’t hit the bank yet but are recorded in the platform’s data.
The Fix: You must reconcile your platform reports with your accounting software every single month. This is why we focus on high-frequency data syncing at Sterlinx Global, to ensure your books match what the platforms are reporting in real-time.
2. Ignoring the $75,000 GST Threshold
In Australia, if your business has a turnover of $75,000 AUD or more (or you expect it to reach that within the next 12 months), you must register for Goods and Services Tax (GST).
Many e-commerce entrepreneurs wait until they see the cash in the bank before registering. However, the ATO views the threshold on a “prospective” basis. If you see a massive spike in sales that suggests you will hit $75,000 soon, you need to register immediately.
Common GST Errors:
- Failing to register on time: This results in back-taxed GST payments that come out of your profit margin.
- International Sales: Even if you sell to customers outside Australia, those sales often count toward your $75,000 threshold, even if you don’t charge GST on them.
- Incorrect GST Credits: Claiming GST “input tax credits” on items where no GST was actually charged (like international software subscriptions or overseas inventory).
The Benefit: Registering correctly and on time allows you to claim back the GST you pay on your business expenses, which can significantly improve your cash flow.
3. The Inventory and COGS Discrepancy
The ATO uses industry benchmarks to determine if your reported figures make sense. If your Cost of Goods Sold (COGS) is disproportionately high compared to your revenue, or if your ending inventory levels look suspicious, you will be flagged for a manual review.
E-commerce businesses often struggle with inventory management, especially when using 3PLs (Third Party Logistics) or offshore warehousing.
Audit Red Flags:
- Large Year-End Write-downs: Suddenly claiming a massive loss on “damaged” or “unsaleable” stock right before the end of the financial year.
- Estimated Figures: Using “round numbers” for inventory instead of actual stocktake data.
- Customs Inconsistency: If your reported inventory purchases don’t match the import data held by Australian Border Force, the ATO will want to know why.
At Sterlinx Global, we help bridge the gap between your physical logistics and your financial reporting. By maintaining a clean audit trail of your inventory movement, we ensure your COGS claims are defensible and accurate.
4. Mismanaging International Sales and Currency Conversion
If you are an Australian business selling to the US, UK, or EU, your tax obligations don’t stop at the border. Conversely, if you are a foreign entity selling to Australians, you may have “Significant Global Entity” (SGE) obligations or Low-Value Imported Goods (LVIG) GST requirements.
The Currency Trap
The ATO requires all income and expenses to be converted into Australian Dollars (AUD) for tax purposes. Many sellers use a single average exchange rate for the whole year, which can lead to significant errors if the AUD/USD or AUD/GBP rate fluctuates.
What you need to do:
- Use the exchange rate applicable at the time of the transaction or an approved ATO daily rate.
- Properly document “forex gains or losses” when transferring money between overseas wallets (like Airwallex or Wise) and your Australian business account.
- Ensure your international VAT and GST filings are consistent across all jurisdictions.
5. Poor Record Keeping and Missing Digital Trails
In the world of e-commerce, the “shoebox full of receipts” has been replaced by a “cloud full of PDFs.” However, many sellers still fail to keep adequate records. Under Australian law, you must keep records for five years.
The ATO is increasingly looking at “split” payments, where a business takes some payments via a website and others via bank transfer or cash. If your point-of-sale (POS) data doesn’t align with your bank statements, an audit is almost certain.
Checklist for Compliance:
- Tax invoices for all purchases over $82.50 (including GST).
- Records of any private use of business assets.
- Detailed logs of international shipping and customs duties paid.
- Monthly reconciliations of all payment gateways (Stripe, PayPal, etc.).
How Sterlinx Global Protects Your E-commerce Business
Navigating the ATO’s requirements shouldn’t keep you up at night. As a Global Tax Compliance Suite, Sterlinx Global Ltd provides an end-to-end solution for businesses scaling in and out of Australia.
We don’t just give you advice and leave you to do the work. We handle the operational execution:
- Bookkeeping & Data Syncing: We pull data directly from your sales channels to ensure 100% accuracy.
- GST & BAS Filings: We calculate and file your Australian GST obligations on time, every time.
- Global Expansion: If you are moving from Australia into the UK or EU, we handle your international tax filings and compliance.
by Ariful | Mar 17, 2026 | EU VAT Updates
Ireland’s Personal Tax Landscape: More Money in Pockets
The Irish government has introduced several measures to ease the burden on individual taxpayers and employees, which directly affects payroll and staff retention for SMEs.
The USC Ceiling Shift
Effective January 1, 2026, the Universal Social Charge (USC) 2% rate ceiling has increased to €28,700. This change is designed to benefit full-time minimum wage workers and middle-to-high earners by keeping more of their income at the lower tax bracket. For business owners, this means your employees are seeing a slight boost in take-home pay without an additional cost to your payroll budget.
Rental and Mortgage Support
If you or your employees are navigating the Irish property market, two key extensions are now in play:
- Rent Tax Credit: Extended through 2028, providing up to €1,000 annually for single individuals and €2,000 for couples.
- Mortgage Interest Tax Relief: This has been extended through 2026. For 2026 claims, a maximum credit of €625 is available.
Boosting Business Growth: R&D and Entrepreneur Relief
Ireland continues to position itself as a hub for innovation. If your business is involved in developing new products or improving existing processes, 2026 brings some very welcome news.
The 35% R&D Tax Credit
The Research & Development (R&D) tax credit rate has officially increased from 30% to 35%. Furthermore, the first-year payment threshold has risen to €87,500. This is a significant benefit for tech-heavy SMEs and startups. Precise bookkeeping is essential to claim these credits accurately, turning your innovation into direct capital.
Entrepreneur Relief Expansion
For those looking at the long game, the lifetime limit for Capital Gains Tax (CGT) entrepreneur relief has increased from €1 million to €1.5 million. This update could potentially save entrepreneurs up to €115,000 when selling their business. It is a clear signal that the 2026 landscape is geared toward rewarding those who build and scale successful enterprises.
The 2026 VAT Shift: Key Dates to Remember
VAT is often a complex hurdle for cross-border businesses. Several adjustments in Ireland and across the EU require immediate attention to ensure your pricing and accounting remain accurate.
Ireland’s 9% VAT Adjustments
Keep a close eye on your calendar for July. From July 1, 2026, a reduced 9% VAT rate will apply to:
- Food and catering services.
- Hairdressing services.
Additionally, the 9% VAT rate on gas and electricity has been extended through 2030 to help manage energy costs. Understanding how these rates affect your specific sales is important for maintaining accurate margins.
EU Cross-Border VAT and E-Invoicing
Across the broader EU, the push for digital transparency is accelerating. France, in particular, has moved forward with strict e-invoicing rules. If you are selling into the French market, you must ensure your systems are compatible with these digital mandates to avoid delays in clearance and potential penalties.
Sustainability and Housing: Green Incentives
The 2026 tax year also emphasizes climate goals. For businesses managing a fleet or providing company cars:
- Electric Vehicles (EVs): A new 6-15% Benefit-in-Kind (BIK) category for EVs is now active.
- VRT Relief: The VRT relief for electric vehicles has been extended to December 31, 2026.
In the property sector, the VAT rate on new completed apartments was reduced to 9% late last year, a move aimed at stimulating the housing supply which continues to influence the market in 2026.
How to Stay Compliant in 2026
Managing tax and VAT across multiple jurisdictions requires more than knowing the rates; it requires proper execution. Missing a deadline or miscalculating a threshold can lead to significant setbacks.
1. Monitor Your Thresholds
Don’t wait until you’ve already passed the limit. Understanding VAT registration requirements allows you to prepare before it becomes an emergency.
2. Streamline Your Bookkeeping
2026 is the year of digital compliance. If you are still using manual spreadsheets, you are at risk. Implementing automated compliance solutions where calculations and filings are handled systematically can protect your business.
3. Seek Expert Help When Scaling
Expansion into the EU, USA, or Canada brings a host of new rules. Knowing when you should hire an accountant is a strategic decision. For many, the answer is “the moment you decide to go global.”
Your 2026 Compliance Checklist
- Update Payroll Systems: Reflect the new USC 2% ceiling of €28,700.
- Review R&D Projects: Prepare documentation to claim the increased 35% credit.
- Adjust Pricing: Prepare for the July 1st VAT changes in Ireland for food and service sectors.
- Check EU E-Invoicing: Ensure compliance if selling to France or other digital-first EU nations.
- Assess EV Benefits: Review your company vehicle policy to take advantage of extended VRT relief.
Frequently Asked Questions (FAQ)
What is the new USC threshold in Ireland for 2026?
As of January 1, 2026, the 2% USC rate ceiling has been increased to €28,700.
When does the new 9% VAT rate apply in Ireland?
The reduced 9% VAT rate for food, catering services, and hairdressing services comes into effect on July 1, 2026.
What is the new R&D tax credit rate?
The Research & Development tax credit rate has increased from 30% to 35%, with the first-year payment threshold rising to €87,500.
Has the entrepreneur relief limit changed?
Yes, the lifetime limit for Capital Gains Tax entrepreneur relief has increased from €1 million to €1.5 million.
What is the extended deadline for VRT relief on electric vehicles?
The VRT relief for electric vehicles has been extended through December 31, 2026.
by Ariful | Mar 17, 2026 | UK Accounting
Welcome to 2026: The New Era of UK Tax Compliance
If you are running a UK Limited Company, you already know that the landscape for tax compliance has shifted significantly over the last few years. HMRC has ramped up its digital transformation, and the “grace periods” we once saw for Making Tax Digital (MTD) are long gone.
As we hit March 2026, many directors, especially those in the fast-paced e-commerce sector, are finding themselves caught in a net of avoidable penalties and structural errors. Running a business is hard enough without getting a “brown envelope” from HMRC because of a simple filing oversight.
Here are the seven most critical mistakes UK Limited Companies are making right now and, more importantly, how you can fix them before the next deadline hits.
1. Transferring Assets Without a Professional Valuation
Many business owners start as sole traders and eventually “level up” to a Limited Company structure. In 2026, we are seeing a surge in entrepreneurs moving inventory, intellectual property, or even property into their new company entities.
The mistake? Doing it based on “gut feel” or historical cost rather than current market value. If you transfer an asset into your company at the wrong valuation, you could trigger an immediate Capital Gains Tax (CGT) liability. This is a major trap for e-commerce brands moving large amounts of stock or proprietary software assets.
The Fix: Always ensure assets are professionally valued before the transfer. Document the process thoroughly. By getting a formal valuation, you establish a clear paper trail that protects you if HMRC ever decides to audit your incorporation. If you’re unsure about the numbers, it is better to pause and get it right than to face a tax bill you didn’t budget for.
2. Ignoring the New 2026 Late Filing Penalty Regime
As of April 1, 2026, HMRC is implementing a stricter penalty regime for late Corporation Tax (CT600) filings. In the past, some directors viewed the £100 fine as a “late fee” they could live with. That era is over.
The new system is designed to penalize repeat offenders more harshly. If you miss your deadline, usually 12 months after your accounting period ends, you face an immediate penalty, and interest on any unpaid tax starts accruing at rates much higher than we saw in previous decades.
The Fix: Don’t treat your filing date as a suggestion. Mark your “soft deadline” three months before the actual due date. If you use a compliance partner, ensure your data is uploaded monthly. This allows for calculation of your liabilities well in advance, so there are no surprises come filing day. You can stay ahead of these changes by regularly checking for UK HMRC updates.
3. “DIY” Making Tax Digital (MTD) Setup Errors
Making Tax Digital for Corporation Tax is now the standard. However, many e-commerce sellers try to handle the software integration themselves. We often see businesses with “broken digital links.” This happens when you manually move data from your Amazon or Shopify dashboard into an Excel sheet and then manually upload it to your accounting software.
HMRC requires a “digital link” from the point of entry to the final submission. If that link is broken by manual data entry, your submission is technically non-compliant, even if the numbers are correct.
The Fix: Automate your data flow. Use direct integrations between your sales platforms and your accounting suite. This ensures the digital links remain intact all the way to HMRC’s servers.
4. Setting Up a Generic “100 Ordinary Shares” Structure
When you first form a company, it’s easy to just tick the box for 100 ordinary shares. However, by 2026, your business might have grown to include family members, key employees, or investors.
The mistake is trying to change this structure “on the fly” without understanding the tax implications. Issuing shares to a spouse or employee after the company has gained significant value can be seen as a form of income or a taxable gift, leading to unexpected Income Tax or National Insurance hits.
The Fix: Think about your share structure from day zero. If you missed that boat, don’t just issue new shares. Talk to a specialist about the most tax-efficient way to restructure. Proper planning now can save you thousands in future dividends and capital gains.
5. Using Your Home Address as Your Registered Office
Privacy is a growing concern in 2026. Many new directors register their home address as the company’s registered office to save on costs. What they don’t realize is that this information becomes public record on Companies House. Anyone, customers, competitors, or cold callers, can find out where you live with a simple search.
Beyond privacy, it also looks less professional to international partners or lenders. If you’re looking at expanding your business globally, a commercial address carries more weight.
The Fix: Use a professional Service Address or Registered Office service. Many accounting firms and formation agents provide this. It keeps your personal life private and ensures all official HMRC and Companies House mail is handled in a professional environment.
6. Failing to Track “Associated Companies”
HMRC has become incredibly strict about “associated companies” in 2026. If you have control over more than one company, or if your close family members do, these companies may be considered “associated.”
Why does this matter? It reduces the thresholds for Corporation Tax rates. Instead of enjoying the lower tax rate on your first £50,000 of profit, that threshold is divided by the number of associated companies. If you have three companies, your lower-rate threshold drops significantly. Failing to declare these can lead to underpaid tax and heavy “failure to notify” penalties.
The Fix: Conduct an annual review of your corporate structure. If you’ve started a new side hustle or a property holding company, let your accountant know immediately. We need to factor this into your tax accounting to ensure your tax brackets are calculated correctly.
7. Poor Documentation of Beneficial Ownership
HMRC and Companies House have increased their scrutiny of “People with Significant Control” (PSC). In 2026, simply listing a name isn’t enough. You must maintain clear records of beneficial ownership, especially if your company is part of a complex structure involving overseas entities or trusts.
For e-commerce sellers with international setups (like a UK Ltd owned by a US LLC), this is a high-risk area for compliance audits.
The Fix: Keep a dedicated PSC register and update it the moment ownership changes by more than 25%. Ensure your filings at Companies House match your internal records exactly. If you are operating across borders, ensure you understand how ownership affects your international registrations.
Why Compliance is Your Best Growth Strategy
It is tempting to view tax filing as a burden, but in 2026, it is actually your best growth strategy. Staying compliant protects your business, builds trust with HMRC, and creates a clean audit trail that makes future fundraising, acquisitions, or exits far smoother. The cost of getting it right is always lower than the cost of fixing mistakes later.
by Ariful | Mar 17, 2026 | US Updates
The Big Myth: Filing vs. Paying
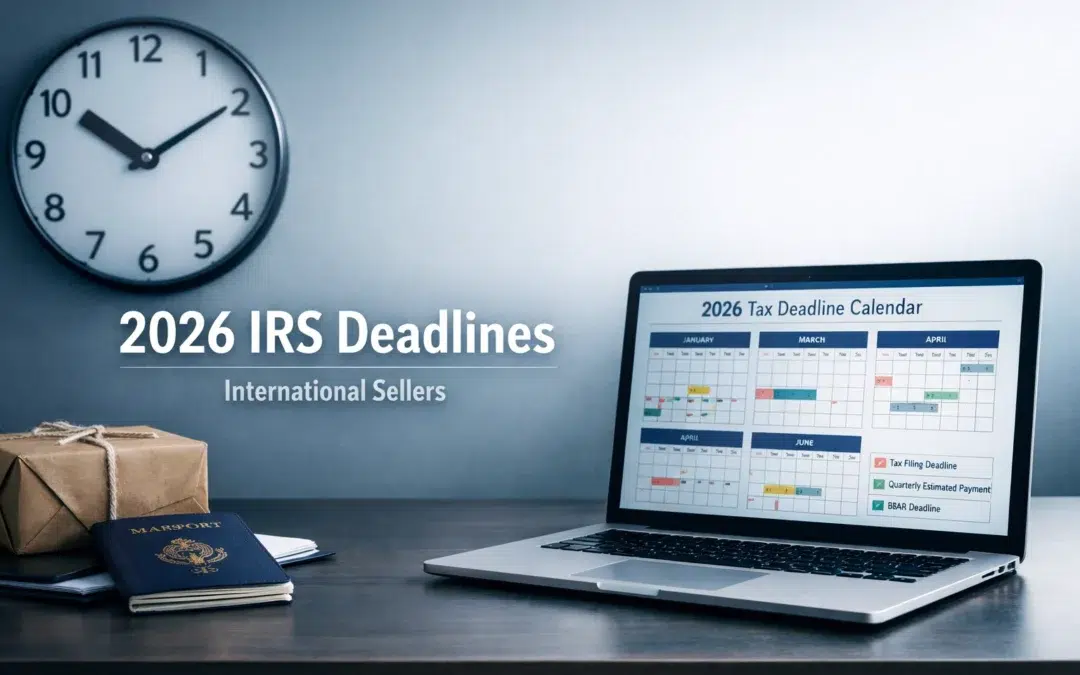
Before we dive into the dates, let’s clear up the biggest misconception in US taxation. An extension to file is not an extension to pay.
Even if you successfully request an extension to move your filing date to October, the IRS expects every penny of tax owed to be paid by April 15, 2026. If you miss that payment date, the interest starts accruing immediately. Don’t let a paperwork delay turn into a debt trap.
March 16, 2026: The First Major Hurdle
For many business structures, the first “finish line” isn’t in April: it’s in March. Because March 15 falls on a Sunday in 2026, the deadline moves to the next business day.
Who needs to act now?
- S-Corporations (Form 1120-S): If you’ve elected S-Corp status, your return is due now.
- Partnerships (Form 1065): This includes multi-member LLCs that haven’t elected to be treated as corporations.
The Strategy: If you aren’t ready to file, you must submit Form 7004 by this date to request a six-month extension. Doing this pushes your filing deadline to September 15, 2026. However, remember the rule above: pay any estimated taxes now to avoid the IRS “late payment” sting.
April 15, 2026: The Critical Deadline for Everyone
This is the day the US tax world revolves around. It is the final deadline for several key groups and the mandatory payment date for almost everyone else.
1. C-Corporations (Form 1120)
If your international business operates as a US C-Corp, your federal income tax return is due today. C-Corps are popular for international sellers looking to reinvest profits or eventually seek VC funding, but they come with strict annual filing requirements.
2. Sole Proprietorships and Single-Member LLCs
If you are an individual seller or a “disregarded entity” (a single-member LLC that hasn’t chosen to be taxed as a corp), your personal tax return (Form 1040 or 1040-NR) is due today.
3. Estimated Tax Payments (Q1 2026)
Success breeds tax obligations. If you expect to owe more than $1,000 in taxes for the 2026 tax year, your first quarterly estimated payment is due today. Keeping up with these keeps your cash flow predictable and avoids year-end “tax shock.”
4. Extension Requests (Form 4868)
If you are an individual (including sole proprietors) and need more time, you must file Form 4868 by today. This grants you an extension to file until October 15, 2026.
The “Invisible” Deadline: Form 5472 for International Owners
This is where many international sellers get caught out. If you own a US LLC that is “foreign-owned” (at least 25% owned by a non-US person) and it is a disregarded entity, you have a specific reporting requirement.
You must file Form 5472 along with a pro-forma Form 1120. The IRS uses this to track transactions between the US company and its foreign owner.
- The Penalty for Missing This: In recent years, the penalty for failing to file Form 5472 or filing it incorrectly has started at $25,000.
Don’t guess on this one. If you are an international seller with a US entity, talk to an expert to ensure your Form 5472 is handled correctly.
June 15, 2026: The Expat Advantage
If you are a US citizen or resident alien living and working outside the United States on the April 15 deadline, you get a “free” two-month extension to file your return. You don’t even need to file a form to get this; it is automatic.
The Catch: Again, the IRS is hungry for its money. Interest on any unpaid tax still starts accruing from April 15. If you owe money, the June extension only helps you avoid the “failure to file” penalty, not the “failure to pay” interest.
October 15, 2026: The Final Countdown
If you filed for an extension back in April, today is the day. There are no further extensions for 2025 tax year returns.
FBAR (Foreign Bank Account Report)
This is arguably the most important date for international sellers with global footprints. If you had a financial interest in or signature authority over foreign financial accounts (including bank accounts, brokerage accounts, etc.) that exceeded $10,000 at any time during the 2025 calendar year, you must file FinCEN Form 114.
While the official deadline is April 15, the IRS grants an automatic 6-month extension to October 15 for everyone. You do not need to request this extension; it’s yours by default.
Checklist for International Sellers in 2026
To ensure you stay compliant and keep your business running smoothly, follow this operational checklist:
- Reconcile your books monthly: Don’t wait until March to look at your 2025 data. Accurate cash flow management and bookkeeping throughout the year make tax season a breeze.
- Confirm your entity type: Are you a disregarded LLC, a C-Corp, or a Partnership? Your deadline depends entirely on this classification.
- Track “Reportable Transactions”: For Form 5472 purposes, keep a log of every time you move money between your personal foreign account and your US business account.
- Check your Sales Tax Nexus: Income tax is only half the battle. Ensure you are also tracking where you have “nexus” for US Sales Tax. Physical or economic presence triggers filing requirements.
- Gather Foreign Bank Data: Start collecting the highest balance of every non-US account held in 2025 for your FBAR filing.
How Sterlinx Global Simplifies US Tax Compliance
Navigating the IRS from outside the US is a daunting task. The rules for international owners are significantly more complex than those for domestic businesses. At Sterlinx Global, we operate as your end-to-end compliance partner.
We don’t just give advice; we deliver results. Our team handles:
- Bookkeeping & Year-End Accounts: Ensuring your data is IRS-ready.
- Tax Calculations: Determining exactly what you owe so there are no surprises on April 15.
- Federal & State Filings: Managing the submission of Form 1120, 1065, 5472, and more.
- Sales Tax Management: Keeping you compliant across the various US states where you sell.



